Navigating Property: Should a Widow Sell Her Home Amid Family Dynamics?
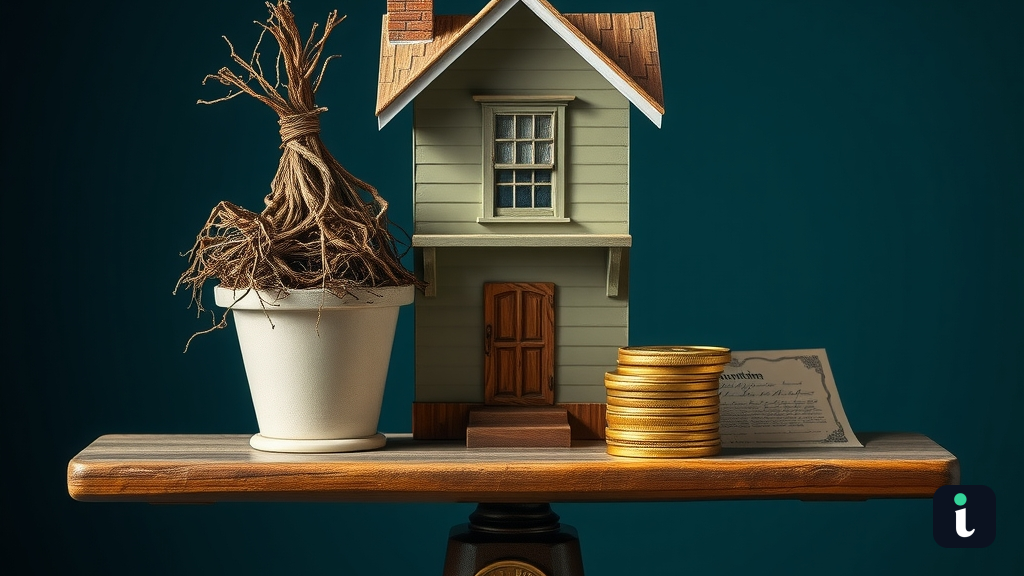
The difficult decision of whether to sell a family home after the death of a partner often intertwines financial considerations with emotional ties and the interests of stepchildren, presenting a less drastic alternative to immediate sale and asset division.
Key takeaways
- For widows, the decision to sell a family home involves balancing personal financial needs, emotional attachment, and potential claims from stepchildren.
- Retaining the home, rather than selling and splitting proceeds immediately, can be a less drastic step, allowing for future planning and stability.
- Estate planning documents, such as wills and trusts, are crucial in clearly defining asset distribution and avoiding disputes among beneficiaries.
- Property market conditions, potential for rental income, and the widow's ongoing living expenses are key financial factors influencing the decision.
The death of a spouse or partner inevitably ushers in a period of profound grief, but it also triggers a cascade of critical financial decisions. Among the most significant for many is the fate of the family home, a primary asset that often represents both emotional security and substantial financial value. For a widow, the question of whether to sell her home, especially when stepchildren are involved, presents a complex dilemma, balancing personal needs with potential familial expectations.
While selling the property and distributing the proceeds might seem like a straightforward solution to some, it is frequently viewed as a more drastic immediate step. Many widows, and their financial advisors, often consider alternatives that allow for a period of stability before making irreversible asset divestments. Such an approach can provide crucial time to assess long-term financial needs and navigate the emotional landscape of loss.
Should a Widow Sell Her Home? Understanding the Financial and Emotional Stakes
The family home typically represents the largest asset in a deceased partner's estate. Its disposition directly impacts the surviving spouse's financial security and lifestyle. For a widow, the decision to sell her home is not merely transactional; it is deeply personal, tied to memories, community, and a sense of permanence. Conversely, retaining a large property can come with significant costs, including property taxes, maintenance, and insurance, which may become burdensome on a single income.
When stepchildren are beneficiaries, the situation gains another layer of complexity. They may have an expectation of inheriting a portion of their parent's estate, which often includes the family residence. Clear estate planning documents, such as a will or trust, are paramount in outlining the deceased's wishes regarding the home and other assets. Without such clarity, disputes can easily arise, potentially leading to costly legal battles and strained family relationships.
The Role of Estate Planning and Legal Frameworks
Effective estate planning is the cornerstone of preventing future conflicts over property. A well-drafted will specifies who inherits what, including the family home. In cases involving a surviving spouse and stepchildren, a common arrangement might involve a life interest trust, where the widow retains the right to live in the home for the remainder of her life, with the property ultimately passing to the stepchildren or other named beneficiaries upon her death. This provides security for the widow while respecting the deceased's wishes for their children.
Without explicit instructions, local inheritance laws come into play, which vary significantly across jurisdictions, including within African nations. In many common law systems, a surviving spouse often has a strong claim to a significant portion of the estate, but this does not always guarantee the outright ownership of the entire family home, especially if there are other legal heirs. Understanding these legal frameworks is crucial for both the widow and the stepchildren to manage expectations and entitlements.
Navigating Property Rights and Beneficiary Interests
The question of property ownership and beneficiary rights becomes particularly acute when the home was owned jointly or solely by the deceased. If the property was held as joint tenants with right of survivorship, ownership automatically passes to the surviving joint owner, typically the widow, outside of the will. However, if it was held as tenants in common, the deceased's share passes according to their will or intestate laws, potentially creating co-ownership with stepchildren or other heirs.
This distinction is vital because co-ownership can lead to disagreements over maintenance, use, and eventual sale. As we reported in Navigating Joint Assets: When One Partner Seeks to Sell the Family Home, situations where one co-owner wishes to sell while another does not can be challenging, often requiring legal intervention to force a sale or buy out the other party. For a widow, this can add immense stress during an already difficult time.
Market Conditions and Financial Implications for Widows
The prevailing real estate market conditions significantly influence the decision to sell. In a robust seller's market, selling might yield a higher price, providing substantial capital for the widow's future. Conversely, a sluggish market, as seen in recent reports like One in Three Home Sellers Cut Prices in September Amid Buyer Hesitation, could mean selling at a discount, potentially diminishing the widow's financial resources. Interest rates also play a role; higher mortgage rates can deter buyers, affecting property values and liquidity.
For a widow in Nigeria or other African markets, the decision might also be influenced by the cultural significance of land ownership and the availability of suitable alternative housing. Property can be a crucial source of intergenerational wealth, and its sale might be viewed differently than in Western markets. The widow must carefully evaluate her financial runway, considering pension income, investments, and any life insurance payouts. Can she afford to maintain the home? Are there opportunities to generate rental income from a portion of the property to offset costs? These are critical questions.
What are the alternatives to selling the family home now?
Beyond an immediate sale, several less drastic options exist. The widow could continue living in the home, using other assets or income to cover expenses. If the estate includes sufficient liquid assets, these could be used to compensate stepchildren for their share, allowing the widow to retain full ownership. Another option is to rent out the property, or a portion of it, generating income to cover costs or provide distributions to beneficiaries, while preserving the asset for a future sale when market conditions are more favorable or personal circumstances change.
Ultimately, the optimal path depends on a confluence of factors: the deceased's explicit wishes, the widow's financial stability, the relationships with stepchildren, and the current economic climate. Professional financial advice and legal counsel are indispensable in navigating these complex waters, ensuring that decisions are made with both emotional sensitivity and financial prudence.
What to watch
- Upcoming property market reports: Monitor local and national real estate indices for trends in home values and sales volumes.
- Interest rate decisions: Central bank announcements on benchmark rates can impact mortgage costs and buyer demand.
- Estate administration timelines: Be aware of legal deadlines for probate and asset distribution, which vary by jurisdiction.
- Family discussions: Open communication with stepchildren and other beneficiaries can help manage expectations and explore mutually agreeable solutions.
For Information Purposes Only. Not Investment Advice. How we work
Iboro William
Iboro William is the founder and editor of Iboro Finance and the builder behind FolioStack, a family of money apps: Samba for airtime, data and bills with Bitcoin cashback, the FolioTrack portfolio tracker, the FolioTrade crypto trading bot and EkpadFile, unlimited cloud storage with watch parties that bring families and loved ones together.
A data analyst by profession, he works daily with SQL, Snowflake and Power BI, and brings the same habit to his writing: read the numbers first, then draw the conclusion.
He has written five books on crypto, money and personal discipline, read by about 15,000 people in 86 countries. On Iboro Finance he explains markets, the economy and crypto for readers in Nigeria, across Africa and in the diaspora.